Investor support for prioritizing climate change is rising again, as concerns around energy security accelerate the renewable energy transition, and as the physical effects of global warming are increasingly felt. It marks a turning point after several years of declining commitments, the Robeco Global Climate Investing Survey 2026 shows.
The sixth annual survey of 300 investors shows they are realistic about climate goals, with most forecasting a ‘too little, too late’ scenario that cannot achieve the Paris Agreement’s aim of limiting global warming to well below 2 °C. A majority across Europe, Asia-Pacific (APAC) and North America already see physical climate risks affecting both asset prices and their own strategic asset allocation in the next few years.
Yet there is also resilience, as most investors remain broadly committed to their own net-zero goals, and are prepared to invest more in climate mitigation, adaptation and resilience strategies. A majority sees increased opportunity for climate investments as a result of the conflicts in the Middle East, as countries seek to reduce their reliance on fossil fuels.
The drive for energy security
“Our 2026 study illustrates what we call the new climate reality,” says Lucian Peppelenbos, Climate and Biodiversity Strategist at Robeco. “While investors remain committed to their net-zero goals, there is a growing realism that the transition is driven by hard economics and hard geopolitics.”
“The drive for energy security is benefiting investments in areas such as renewables, battery storage and grids. The new climate reality is also a realization that physical risks are here now, not in a distant future. We believe this will increasingly drive investor sentiment in the next few years.”
Main survey results
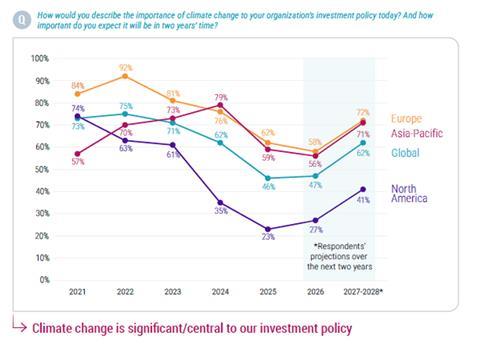
The number of investors globally who make climate change a significant part of, or central to, their investment policy has risen slightly from 46% in 2025 to 47% this year. This rises to 58% in Europe and 56% in APAC. In North America, which saw a significant drop in climate investing in 2024 due to an anti-ESG backlash, the figure rose from 23% to 27%.
As seen in previous years, investors remain realistic about the transition to net zero. Of the four possible transitions, a majority of 47% expect a ‘too little, too late’ scenario, slightly down from last year. A further 28% expect a ‘disorderly’ transition, and 7% expect a ‘hot house world’ in which emissions continue to rise unchecked. Only 19% expect an ‘orderly’ transition to take place.
Despite their lack of confidence in the world’s ability to achieve the Paris goals, most investors are staying the course on their own net-zero commitments. Some 64% of investors who have publicly backed net zero say their investment approach is unchanged. However, nearly a third said the road ahead has become more difficult, and they have reconsidered their investment approach as a result.
Physical risks, the Middle East and AI
This year’s survey points to two factors explaining why investors are staying the course, despite the backtracking by governments on climate policies. The first is increased awareness of the near-term materiality of physical climate risk, while the second is expectations that energy security and also artificial intelligence will accelerate the energy transition.
Two-thirds of investors (66%) said they expect physical climate risks to have a moderate to significant impact on asset prices over the next five years. This rises to 82% over 10 years and 87% over 20 years. Almost two-thirds (63%) expect physical risks to change their strategic asset allocation in the next five years, as well as other parts of the investment process such as capital market assumptions and asset manager selection.
Regarding the Middle-East conflict, 75% of investors globally thinks the closure of the Strait of Hormuz will moderately or significantly accelerate the transition to renewables, reducing the need to rely on fossil fuels, rising to 78% in Europe and 83% in APAC.
Investors are also more positive about the benefits of AI than its drawbacks in energy and water use. Globally, 63% thought it would accelerate the development of sustainable infrastructure such as wind and solar farms, while 57% said it would have a positive impact on accelerating the transition toward renewable energy.
Investing in solutions and the transition
Investing in climate solutions remains popular. Globally, 72% of investors aim to invest more in climate mitigation methods such as renewable energy, and in climate adaptation techniques such as flood prevention. Part of this attraction lies in climate solutions being perceived as a growth area, and not just a means of tackling global warming.
And climate transition finance is further gaining in popularity, actively funding high-carbon-emitting industries, such as coal-fired power generation and traditional heavy industries such as steel, cement, chemicals, aviation or construction, to facilitate the decarbonization of their operations. This follows the mantra of financing reduced emissions rather than reducing financed emissions.
Here, green bonds are the most widely used type of climate transition finance among investors, with 47% of global investors holding them. The next most popular methods are in equity funds or strategies (38%), sustainability-linked bonds (34%) and climate transition bonds (25%).
You can read the full climate survey on Robeco’s website here »
Important information – Capital at risk
This information refers only to general information about Robeco Holding B.V. and/or its related, affiliated and subsidiary companies (“Robeco”), Robeco’s approach, strategies and capabilities. This is a marketing communication solely intended for professional investors, defined as investors qualifying as professional clients, who have requested to be treated as professional clients or who are authorized to receive such information under any applicable laws. Unless otherwise stated, the data and information reported is sourced from Robeco, is, to the best knowledge of Robeco, accurate at the time of publication and comes without any warranties of any kind. Any opinion expressed is solely Robeco’s opinion, it is not a factual statement, and is subject to change, and in no way constitutes investment advice. This document is intended only to provide an overview of Robeco’s approach and strategies. It is not a substitute for a prospectus or any other legal document concerning any specific financial instrument. The data, information, and opinions contained herein do not constitute and, under no circumstances, may be construed as an offer or an invitation or a recommendation to make investments or divestments or a solicitation to buy, sell, hold or subscribe for financial instruments or as financial, legal, tax, or investment research advice or as an invitation or to make any other use of it. All rights relating to the information in this document are and will remain the property of Robeco. This document may not be copied or used with the public. No part of this document may be reproduced or published in any form or by any means without Robeco’s prior written permission. Robeco Institutional Asset Management B.V. has a license as manager of UCITS and AIFs of the Netherlands Authority for the Financial Markets in Amsterdam.
Parts of the marketing material may involve the use of AI-assisted tools to support the creation and review of marketing materials. These tools are designed to help ensure greater consistency and efficiency. All outcomes are reviewed by human evaluators.
Australia
This document is distributed in Australia by Robeco Hong Kong Limited (“RHK”) (ARBN 156 512 659). RHK is exempt from the requirement to hold an Australian financial services license under section 911A(2)(ep) of the Corporations Act 2001 (Cth) in respect of the financial services it provides. RHK may only provide financial services to wholesale clients under that exemption. RHK is regulated by the Securities and Futures Commission under the laws of Hong Kong, which may differ from Australian laws. This document is distributed only to “wholesale clients” within the meaning of the Corporations Act 2001 (Cth). It is not intended for distribution or dissemination, directly or indirectly, to any other class of persons. This document is not intended for public distribution in Australia.
Hong Kong
This document is issued by Robeco Hong Kong Limited, which is regulated by the Hong Kong Securities and Futures Commission (“SFC”). The contents of this document have not been reviewed by the SFC. Investment involves risks. This information does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation for any security.
New Zealand
In New Zealand, this document is only available to “wholesale investors” within the meaning of clause 3(2) of Schedule 1 of the Financial Markets Conduct Act 2013 (‘FMCA’). This document is issued by Robeco Hong Kong Limited which does not have a place of business in New Zealand.
Singapore
This information is for informational purposes only and should not be construed as an offer to sell or an invitation to buy any securities or products, nor as investment advice or recommendation. The contents of this document have not been reviewed by the Monetary Authority of Singapore (“MAS”). Robeco Singapore Private Limited holds a capital markets services licence for fund management issued by the MAS and is subject to certain clientele restrictions under such licence. An investment will involve a high degree of risk, and you should consider carefully whether an investment is suitable for you.
Switzerland
Robeco Switzerland Ltd is licensed by the Swiss Financial Market Supervisory Authority FINMA as a manager of collective assets.
United Kingdom
This information is provided by Robeco Institutional Asset Management UK Limited, 30 Fenchurch Street, Part Level 8, London EC3M 3BD, registered in England no.15362605. Robeco Institutional Asset Management UK Limited is authorised and regulated by the Financial Conduct Authority (FCA – Reference No: 1007814).
US
This document may be distributed in the US by Robeco Institutional Asset Management US, Inc. (“Robeco US”), an investment adviser registered with the US Securities and Exchange Commission (SEC). Such registration should not be interpreted as an endorsement or approval of Robeco US by the SEC. Robeco B.V. is considered “participating affiliate” and some of their employees are “associated persons” of Robeco US as per relevant SEC no-action guidance. Employees identified as associated persons of Robeco US perform activities directly or indirectly related to the investment advisory services provided by Robeco US. In those situations, these individuals are deemed to be acting on behalf of Robeco US. SEC regulations are applicable only to clients, prospects and investors of Robeco US. Robeco US is wholly owned subsidiary of ORIX Corporation Europe N.V. (“ORIX”), a Dutch Investment Management Firm located in Rotterdam, the Netherlands. Robeco US is located at 90 Park Avenue, 21st Floor, New York, NY 10016.
© Q2/2026 Robeco