Content (274)
-
 White papers
The expanding role of investment grade private credit in institutional portfolios
U.S. investment grade private corporate credit, debt issued directly to a small group of institutional lenders rather than sold on the public bond market, is seeing increased interest from asset allocators. The market predates the below-investment grade direct lending market by decades, driven largely by life insurers as a core fixed income allocation.
-
 White papers
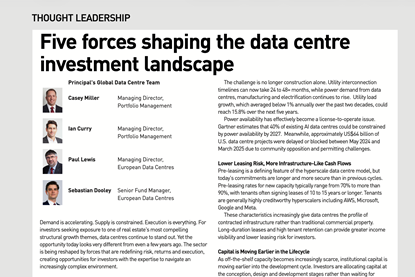
Five forces shaping the data centre investment landscape
Demand is accelerating. Supply is constrained. Execution is everything. For investors seeking exposure to one of real estate’s most compelling structural growth themes, data centres continue to stand out.
-
 White papers
Four for fixed income: The themes driving bond markets
Many investors entered 2026 expecting slower growth, cooling inflation, and eventual Federal Reserve rate cuts. Instead, markets have faced a more complicated reality, with geopolitical tensions rising, oil prices moving higher, rates backing up, and investors pricing a meaningful probability of additional Fed tightening. Yet the U.S. economy remains resilient, inflation has generally improved, and productivity gains driven by technology and AI continue to support growth.
-
 White papers
How U.S. middle market direct lending complements and enhances European portfolios
Direct lending continues to expand across Europe as institutional and sophisticated high-net-worth investors recognize the attractive opportunities available. Demand for private credit, and specifically middle market direct lending, is growing faster than supply, prompting investors to look beyond their domestic markets.
-
 White papers
Cutting through the noise: Why lower and core middle market direct lending still delivers value in clients’ portfolios.
A long-form perspective from Principal Alternative Credit on what investors should be watching—and what the headlines are missing—in today’s private credit market.
-
 White papers
When safe isn’t safe
Artificial intelligence is real, powerful, and beginning to reshape the economy. What is yet to be determined, however, is whether financial markets have pulled forward too much of this future too quickly, and into too narrow a set of stocks. As AI becomes the dominant market narrative, the distinction between revolutionary technology and durable investment return rarely mattered more.
-
 White papers
Fixed income: Resilient, but more selective
Fixed income enters the second half of the year in a relatively strong position, though the path forward has become less certain. Yields remain attractive, and fundamentals are broadly stable, but tighter spreads and shifting policy expectations are leaving less room for surprises. The result is a market that still offers opportunity, but one where outcomes are increasingly shaped by how well investors navigate changing conditions rather than broad market trends.
-
 White papers
June FOMC meeting: A new era for the Fed
At its June meeting, Kevin Warsh’s first as chair, the Federal Open Market Committee (FOMC) left the target range for the federal funds rate unchanged at 3.50%-3.75% for a third consecutive meeting.
-
 White papers
The growing role of capex in inflation dynamics
Last week’s inflation report, and expectations of a U.S.-Iran agreement, have eased inflation concerns. However, the inflation outlook is not defined by oil dynamics alone. AI capex, combined with rising global expenditures on defense and energy security, is reinforcing demand for commodities, suggesting a durable capex cycle could lift producer costs and put upward pressure on inflation in the near term. Against this backdrop, investors can seek thematic exposure while building resilience against inflation.
-
 White papers
May CPI report: War impact remains contained, allowing the Fed to stay on hold
Today’s inflation report reflects ongoing price pressures tied to the Middle East conflict, though the impact remains relatively contained. Headline inflation, primarily driven by energy, rose 0.5% in May, as expected, lifting the annual rate to 4.2%, the highest in over three years. However, inflation concerns were eased by goods deflation and a lower-than-expected Core CPI reading of 0.2%. Even so, the fluid situation in the Middle East suggests the risk of higher energy prices for longer, along with second-round inflation impacts, persists.
-
 White papers
Rethinking diversification in a tightly linked global market
Despite the S&P 500’s resilience amid the Middle East conflict, its concentration remains a concern, underscoring the importance of diversification. However, achieving diversification has become more challenging as global markets remain interconnected through AI supply chains, reducing regional differentiation. At the same time, regions most exposed to the Middle East conflict have lost their appeal as effective diversifiers. Against this backdrop, investors must reassess their approach, with a focus on differentiated and independent growth drivers to build more resilient portfolios.
-
 White papers
Why positive surprise matters in small-cap growth
In small-cap growth, returns are driven less by current earnings and more by shifts in long-term expectations. Because valuations hinge on those expectations, when a company delivers results or provides signals that exceed consensus expectations, even small upward revisions can have an outsized impact on both earnings and valuations. For investors, recognizing these inflections early is critical in a segment where markets often underreact.