
Harrison Street Asset Management (Harrison Street) is a $110+ billion / € 95+ billion global leader in real assets, investing across real estate, infrastructure, and credit strategies. The firm combines mid-market specialization with institutional scale, offering investors differentiated access and long-term value across essential real asset strategies.
Built on a foundation of expertise, integrity, and innovation, Harrison Street applies deep market knowledge, proprietary data insights, and disciplined execution to help investors achieve their long-term objectives. With a cycle-tested track record and unwavering commitment to alignment, transparency, and partnership, the firm has earned the trust of more than 900 institutional investors globally, the majority of whom are multi-fund partners.
Headquartered in Chicago, Toronto, and London, Harrison Street’s 600+ professionals across 20 offices unite global perspective with local insight. The firm’s leadership team - experienced across multiple market cycles - has built a culture rooted in collaboration, accountability, and long-term partnership, continuing to advance HSAM’s mission of creating enduring value alongside its investors.
Investment principles & strategy
HSAM Europe, the European investment platform of Harrison Street, provides real estate and asset-backed credit across Western Europe, complemented by selective thematic equity capabilities in sectors supported by long-term structural demand. Built on RoundShield’s investment heritage since 2013, the platform offers flexible capital solutions to the mid-market on behalf of institutional investors. The team combines deep local origination relationships and specialist underwriting with integrated asset management and restructuring capabilities, supported by Harrison Street’s global real estate expertise. Its strategies span senior secured lending, opportunistic financing and selective thematic equity, underpinned by disciplined underwriting, a focus on underlying asset value and active asset management to protect capital and create value.
Sector Forecasts
RESIDENTIAL: European Build-to-Rent (“BTR”):
Across many European cities, residential supply continues to lag demand, with household growth exceeding completions by an average of 35% since 2018. The largest shortages are in high-conviction markets such as Spain and Ireland, where construction has failed to keep pace with population growth. While permits are rising, they remain well below prior peaks, and elevated costs, economic uncertainty, and sector challenges are expected to keep supply constrained. Against this backdrop, build-to-rent benefits from strong structural demand driven by housing undersupply and declining affordability. At the same time, shrinking private rental stock is increasing the appeal of professionally managed, institutionally owned rental housing.
Although BTR is still a nascent sector in the UK and Europe, its underlying fundamentals and acceptance as a viable housing solution have created an attractive investment opportunity. Demand is being driven by structural housing undersupply and a secular shift towards renting, as macroeconomic pressures continue to make homeownership less attainable. Household income growth has not kept pace with home price inflation, while tighter mortgage markets and higher interest rates have further constrained affordability. At the same time, the available private rental stock—particularly in the UK and Spain—has contracted as elevated financing costs and stricter regulations have led many private landlords to exit the market. Unlike traditional buy-to-let apartments, BTR units are professionally managed and often held in long-term portfolios, giving tenants a higher quality experience than what would otherwise be available from individual landlords.
OTHER: European Student Accommodation:
Continental European student housing continues to demonstrate strong fundamentals, with occupancy exceeding 95% and rents increasing an average of 9% in AY2025-26, significantly ahead of inflation. Performance has been supported by continued enrollment growth, particularly in Spain, Ireland, and Italy, led by rising international student populations. This trend is especially supportive of PBSA demand, as international students are significantly more likely to live in purpose-built accommodation. Coupled with limited housing supply and provision rates as low as 4% in some cities, growing enrollment and persistent undersupply continue to create an attractive long-term investment opportunity across European student housing markets.
European Senior Housing:
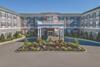
Europe’s aging population continues to drive strong demand for senior housing, supporting record occupancy levels of 94% and high single-digit income growth across key markets. Investor interest remains robust, with transaction volumes reaching a record €15.2 billion. Looking ahead, demographic tailwinds, limited new development, and an aging existing stock are expected to keep demand ahead of supply. Opportunities are further supported by growing capital needs among operators and increasing market consolidation. Countries with affluent senior populations, higher self-pay requirements, and established private-sector participation remain particularly attractive, reinforcing the sector’s compelling long-term investment outlook.
European Self Storage:
European self storage continues to benefit from strong fundamentals, with resilient occupancy, healthy rental growth, and increasing institutional investor interest. The sector has demonstrated defensive characteristics through recent market volatility, supported by operators’ ability to capture rental growth through shorter lease terms. While development activity has accelerated, Europe remains significantly underpenetrated relative to more mature markets, providing a substantial runway for future growth. Demand is expected to remain strong as urbanization, smaller living spaces, and evolving business storage needs increase utilization. These dynamics, combined with moderating new supply, continue to support an attractive long-term outlook for the sector.
Luxury Hospitality:
The European luxury hospitality and branded residences sector is benefiting from rising global wealth, growing demand for experiential travel, and a shortage of premium supply. Supply growth is expected to lag visitor growth, while luxury resort RevPAR has increased around 70% since 2019. Approximately 72% of Europe’s luxury hotel stock is concentrated in major city centres, leaving amenity-rich resorts scarce. Branded residences command average pricing premiums of approximately 30%, while their pre-sales can provide upfront capital, helping to de-risk hotel development and enhance returns. Europe remains underpenetrated in both sectors, creating an attractive opportunity to capitalise on demand for experiential travel and hospitality-backed second-home ownership.
Industrial:
Selective financing opportunities exist in high-quality logistics assets in favourable supply/demand markets, underpinned by strong growth dynamics and with requirements that cannot be met by traditional lenders due to regulatory capital constraints and more conservative risk appetites, as well as in assets approaching lease events where active asset management can unlock additional value.
Office:
The office sector is undergoing a period of significant repricing, driven by lease rollover risk, refinancing needs and increasing ESG-related capital expenditure requirements. An undersupply of Class A / higher-quality assets (some markets experiencing sub-5% vacancy) has created an attractive opportunity to selectively acquire well-located assets at discounted valuations in order to bring them up to institutional tenant quality, as well as ESG-compliant.
Strategic corporate development
Harrison Street Asset Management is a global platform built to deliver scale, innovation, and performance across real assets. With extensive capabilities in real estate, infrastructure, and credit, HSAM provides investors differentiated access to strategies supported by distinct demand drivers and sectors less correlated to the broader economic cycle.
The firm’s leadership team, with decades of experience building and managing investment platforms through multiple market cycles, maintains a collective focus on discipline, alignment, and collaboration, ensuring HSAM remains nimble and forward-looking.
Leveraging its global reach, local expertise, and culture of partnership, HSAM continues to innovate and deliver differentiated mid-market real asset strategies across the risk-return spectrum. Pioneering Real Assets. Powering What’s Next.
Performance verification
Performance return cashflows for Harrison Street European Fund I, Harrison Street European Fund II and Harrison Street Fund III have been verified by the accounting firm Ernst & Young through 31 December 2025 . Returns are calculated in accordance with INREV guidelines. The calculated performance is thoroughly checked in-house by Harrison Street as part of a multi-stage process.
Performance return cashflows for Harrison Street’s funds have been verified by the accounting firm Ernst & Young through December 31, 2025. Returns are calculated in accordance with INREV guidelines. The calculated performance is thoroughly checked in-house by Harrison Street as part of a multi-stage process.
COMPLIANCE STATEMENT
The information contained herein is for the sole purpose of providing general information to institutional investors about HSAM and its affiliates. Certain subsidiaries are registered with appropriate regulatory authorities. No representation is made concerning the accuracy of the information compiled herein, and no guarantee or assurance is given that any forecast or opinion in these materials will be realized. The information contained herein is not investment advice and may not be construed as the promotion or marketing of any services or financial product sponsored or provided by HSAM and its affiliates. All information herein is as of March 31, 2026, unless otherwise stated, and Harrison Street undertakes no obligation to update any such information. The figures and data herein are generally comprised of the aggregated data of investment advisors owned in whole or in part by HSAM.